Unit economics CAC LTV is the CEO-level view of what it costs to acquire a customer, what that customer contributes economically over time, and how quickly the business recovers its investment. It matters because revenue growth alone does not prove that growth is profitable, repeatable, or financeable.
For Education and B2C businesses, the central question is not whether marketing can produce more demand. It is whether each additional customer creates enough contribution margin, on a reliable enough timetable, to support further investment without creating a cash constraint.
CAC, LTV, margin, and payback are therefore not finance metrics to review after the marketing decision. They are the metrics that should shape the decision before you scale traffic, hire more execution, or change agencies. Review our customer acquisition cost guide for cost-boundary decisions, then compare the result with the marketing ROI framework.
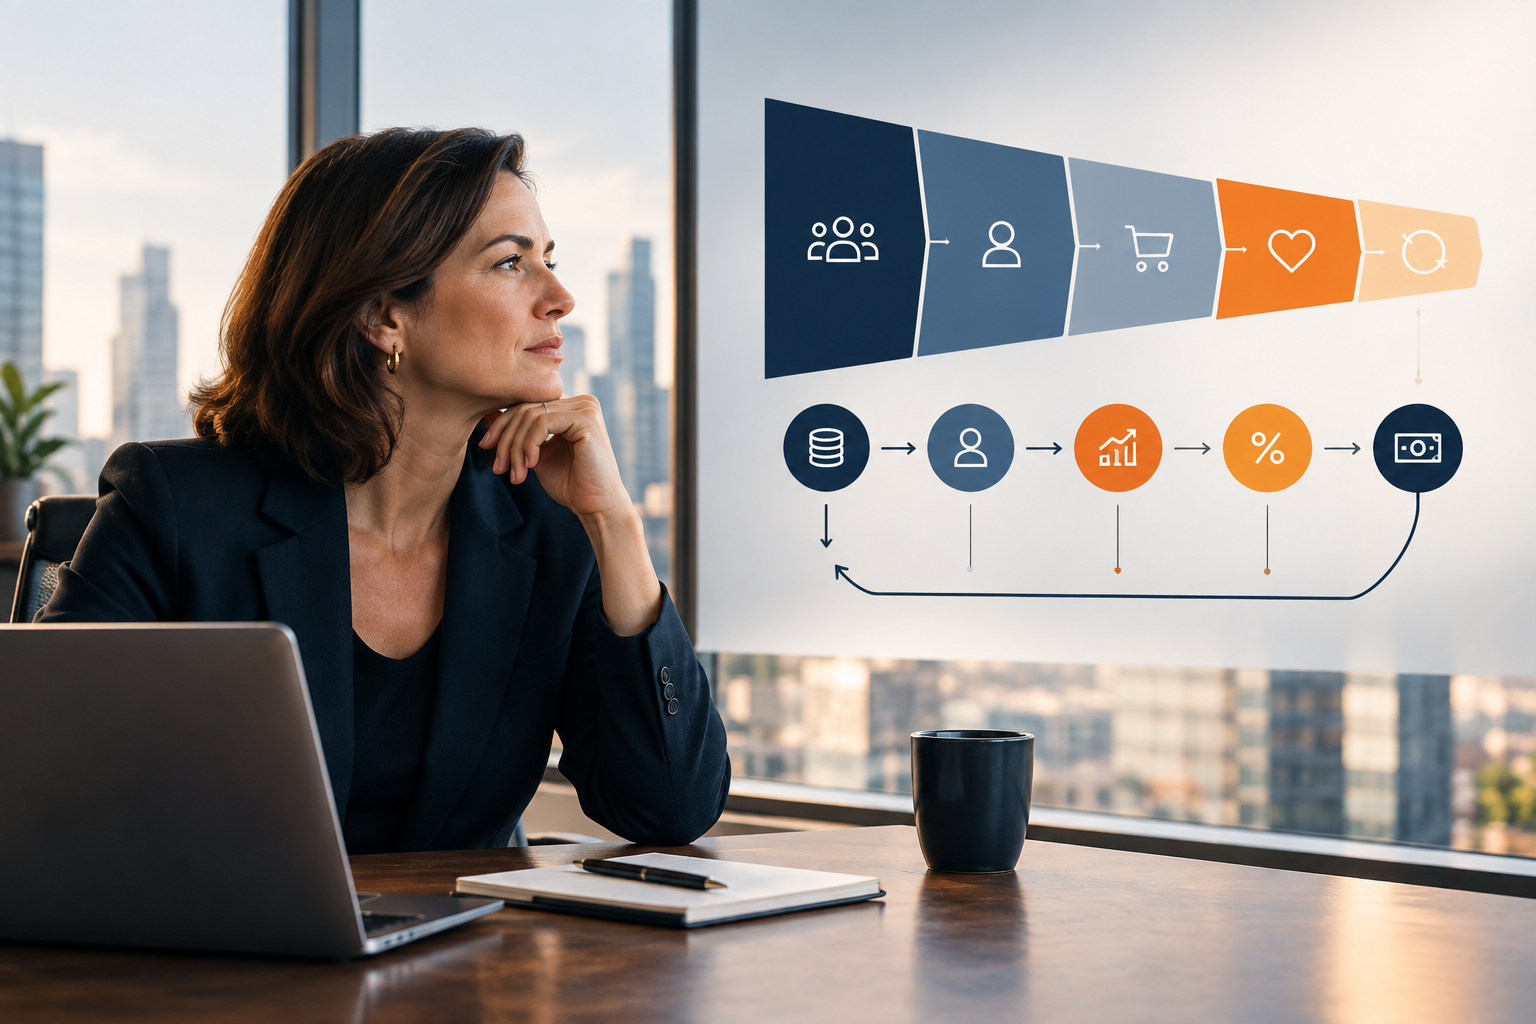
What is unit economics CAC LTV, and why does it matter to growth?
Unit economics CAC LTV describes the economic relationship between acquiring a customer and serving that customer over time. CAC is the cost required to acquire a new customer. LTV is the value that customer produces across the relationship. The difference between them, adjusted for margin and timing, determines whether acquisition supports profitable growth.
The phrase is often reduced to a ratio. That is too simplistic. A business can show an attractive eventual LTV relative to CAC and still face a serious growth problem if it takes too long to recover acquisition costs, margins are thin, refunds are rising, or delivery costs increase with every new customer.
A useful executive view asks four connected questions:
- What does it cost to acquire a customer through each meaningful channel or customer segment?
- How much contribution does that customer create after direct costs, refunds, and variable delivery costs?
- How long does it take to recover the acquisition investment?
- Can the company fund growth at that recovery speed without damaging cash position or service quality?
Why is revenue growth not enough to prove that acquisition is working?
Revenue can rise while acquisition economics deteriorate. A company may be buying customers at an increasing cost, discounting too heavily to convert them, carrying high fulfillment costs, or attracting customers who refund, disengage, or fail to repurchase.
In Education businesses, this can happen when enrolment rises but student completion, renewal, upgrade, or support economics weaken. In B2C, it can happen when a first purchase looks efficient while repeat behavior fails to materialise or fulfilment costs absorb the apparent margin.
Growth is valuable when it creates durable contribution and recoverable cash. It is dangerous when it only increases gross revenue while increasing the capital required to maintain it.
Why is LTV an estimate rather than a promise?
LTV is an estimate because it depends on observed customer behavior over time. It changes with retention, repurchase frequency, pricing, product mix, refunds, margin, and customer support requirements. A forecast based on immature cohorts may look stronger than the underlying evidence supports.
The right question is not, “What could a customer be worth?” It is, “What have comparable customers contributed, after relevant variable costs, over a period that is mature enough to inform this decision?”
Why should you understand unit economics before scaling traffic or media spend?
You should understand unit economics before scaling because more traffic amplifies the system already in place. If conversion is weak, the offer is mismatched, delivery costs are excessive, or retention is poor, additional spend magnifies the underlying failure rather than solving it.
Paid acquisition is not automatically a problem, and neither is an agency that manages it. The issue is whether the commercial system can convert additional demand into margin and cash at an acceptable pace.
Before expanding acquisition investment, a CEO should be able to explain what constraint is currently binding:
- Attention is expensive because the market, creative, channel mix, or targeting is inefficient.
- Demand is reaching the business but too few prospects progress into qualified sales conversations or completed purchases.
- Sales conversion is weak because the offer, proof, pricing structure, sales process, or buyer fit is misaligned.
- First-purchase conversion works, but refunds, delivery costs, retention, or repeat purchase behavior erode customer value.
- Customer economics are sound, but cash recovery is too slow for the company’s current growth ambition.
What happens when you scale a funnel that does not recover CAC fast enough?
When CAC is recovered slowly, every increment of growth consumes working capital before it generates cash for reinvestment. The company can appear successful at the revenue level while becoming increasingly dependent on external cash, payment terms, or delayed operating investment.
This is especially important where sales are paid upfront in one period but delivery costs extend over months, or where customers pay in instalments while marketing costs are incurred immediately. The eventual LTV may be attractive, but the cash profile can still constrain growth.
Payback does not tell you whether to spend more in isolation. It tells you whether the business can afford the speed at which it is currently growing.
How does unit economics CAC LTV fit into the wider funnel and unit economics model?
Unit economics CAC LTV sits across the entire revenue machine, not just at the advertising account or checkout page. Acquisition begins with demand creation, but customer economics continue through sales conversion, onboarding, fulfilment, retention, repeat purchase, and support.
A CEO-level unit economics model connects commercial stages that are often reviewed separately. Marketing may report leads. Sales may report closes. Operations may report delivery capacity. Finance may report gross margin. The business needs one integrated view of how those stages create or destroy contribution.
The broader perspective in Unit Economics: A CEO-Level Growth Guide and Unit Economics Model: A CEO-Level Growth Guide is simple: do not treat a downstream economics problem as a top-of-funnel problem just because it first appears in a CAC report.
Where does the funnel end and customer economics begin?
The funnel does not end at the sale. A sale is the point at which a business acquires both revenue and an obligation to deliver value. The true economic result depends on whether customers pay, remain engaged, complete the experience, request refunds, require extensive support, renew, upgrade, or buy again.
For a course provider, an initial enrolment may be only the beginning of the economic story. For a subscription business, the first payment tells you little without retention evidence. For a product-led B2C business, contribution depends on fulfilment, returns, service load, and repeat purchase behavior.
Why should you compare cohorts instead of relying only on blended averages?
Blended averages can hide meaningful changes. A blended CAC may look stable while a newer channel, offer, audience, or campaign is acquiring customers with lower retention or higher refund rates. Equally, a blended LTV may be inflated by older customers who were acquired under better economics.
Cohort analysis compares groups of customers acquired in similar periods or through similar routes. It helps leadership see whether the current acquisition model is producing customers with comparable outcomes to prior periods.
You do not need an elaborate reporting exercise to act on this principle. You need enough visibility to distinguish a genuine improvement in customer economics from a blended average that conceals deterioration.
Which inputs matter most when you evaluate unit economics LTV CAC?
The most important inputs are the ones that materially change contribution, cash recovery, and decision quality. For most Education and B2C businesses, that means acquisition costs, new customers, revenue collected, direct delivery costs, refunds, retention, repeat purchases, sales costs, and timing.
Foundational resources on customer acquisition cost and customer lifetime value rightly connect acquisition spending to the profitability of the customers acquired. The CEO requirement is to apply those definitions consistently to the specific decision at hand.
What should count in CAC?
CAC should include the economically relevant costs required to acquire customers through the channel or commercial motion being evaluated. Depending on the business, this can include media spend, creative production, agency fees, internal acquisition labour, sales commissions, lead-generation tools, or event costs.
The correct definition depends on the decision. A channel-level decision may require a narrower view of directly attributable costs. A company-level planning decision may require a fuller view of the resources needed to sustain acquisition. The critical rule is consistency. Do not compare a narrow CAC in one period with a fully loaded CAC in another and call it improvement.
What should reduce the value you assign to LTV?
LTV should be reduced by the costs that rise when a customer is acquired and served. These often include refunds, chargebacks, payment processing, fulfilment, customer support, coaching or service delivery, commissions, and other variable costs.
Revenue-based LTV is not the same as economic value. If a customer spends repeatedly but each transaction requires substantial variable delivery, support, or fulfilment expense, revenue can significantly overstate the contribution available to recover CAC and fund growth.
| Input | Why it matters | What it can reveal |
|---|---|---|
| Acquisition cost | Shows the investment required to create a customer. | Channel efficiency, rising competition, or incomplete cost allocation. |
| First-purchase contribution | Shows whether the initial transaction begins recovering CAC. | Pricing, discounting, margin, and delivery economics. |
| Refund and return behavior | Reduces realised customer value. | Offer mismatch, expectation gaps, or delivery issues. |
| Retention and repeat purchase | Determines whether value compounds after acquisition. | Product value, customer experience, and monetisation strength. |
| Payback timing | Shows when acquisition investment returns as contribution. | Cash pressure and capacity to reinvest. |
How should a CEO calculate and map CAC, LTV, margin, and payback?
A CEO should use simple, decision-relevant calculations that reflect the actual business model. Precision matters, but false precision is worse than a transparent estimate with clear assumptions.
The formulas below are deliberately high level. They provide a common language for commercial and finance teams, not a substitute for judgment about cohort maturity, cost allocation, or customer behavior.
How is CAC calculated?
A basic CAC calculation is:
CAC = relevant acquisition costs ÷ new customers acquired in the matched period
The matched period matters. Costs and customers must relate to the same acquisition activity and timing. If a long sales cycle separates marketing spend from closed customers, a simple monthly calculation may produce misleading conclusions.
How should you calculate LTV without mistaking revenue for profit?
A practical contribution-margin LTV estimate begins with realised customer revenue and subtracts the variable costs required to earn and serve that revenue.
Contribution-margin LTV = customer revenue over the relevant period − variable costs associated with that customer
For recurring or repeat-purchase models, the estimate should reflect retention and observed purchasing behavior. For one-time purchase businesses, it should reflect whether customers actually make additional purchases and the margin attached to them.
Consider a hypothetical business that acquires a customer for $120. The customer produces $300 in collected revenue over a relevant observation period, but direct delivery, payment, support, refunds, and variable fulfilment total $150. The customer’s contribution-margin LTV is $150, not $300. The economic spread above CAC is therefore much narrower than a revenue-only calculation suggests.
How do you calculate the CAC payback period?
CAC payback is the time required for a customer or cohort to generate enough contribution margin to recover the acquisition investment.
CAC payback period = CAC ÷ average contribution margin generated per customer per period
Using the hypothetical example, if the customer generates contribution margin steadily over several months, payback depends on the timing of that contribution, not merely the eventual total. If most contribution arrives late, the business carries the CAC burden for longer.
The key unit economics CAC LTV payback period question is not whether payback is universally “good” or “bad.” It is whether payback works within your sales cycle, cash reserves, gross margin profile, financing position, and operating capacity.
What is the difference between unit economics CAC vs LTV?
Unit economics CAC vs LTV is the difference between an upfront investment and the economic value produced after that investment. CAC tells you what you pay to win a customer. LTV tells you what that customer contributes over time. Margin and payback show whether that relationship is commercially viable and financially manageable.
Neither metric is sufficient alone. CAC can be low while acquired customers are unprofitable. LTV can be high while the business takes too long to collect enough cash to sustain acquisition at scale.
Why can a strong LTV still create a growth problem?
A strong eventual LTV can hide slow payback, deferred collections, weak initial margins, or a costly delivery model. This is common in businesses that acquire customers efficiently on paper but cannot recover the investment until long after the original marketing outlay.
The result is a growth paradox: demand is working, customers may eventually be valuable, but the company cannot responsibly accelerate because each new cohort increases the cash required before contribution arrives.
Why can a low CAC still be misleading?
A low CAC can reflect genuine efficiency, but it can also reflect incomplete cost inclusion, underinvestment in acquisition, a narrow pool of easily converted existing demand, or customers who purchase cheaply but create poor downstream economics.
It can also signal that marketing is producing enquiries that convert initially but are poorly aligned with the offer. Rather than calling these “low-quality leads,” identify the actual failure mode: Are prospects outside the intended customer profile? Are they responding to a message that the offer does not fulfil? Are they converting through discounting and later refunding? Do sales conversations reveal a recurring mismatch in need, budget, urgency, or decision authority?
What do healthy or broken CAC LTV patterns look like without generic benchmarks?
Healthy acquisition economics are defined by improving or stable contribution, reliable payback, consistent cohort behavior, and cash recovery that fits the company’s operating reality. Broken economics show up when rising acquisition cost is not matched by customer value, conversion, or margin.
Universal benchmarks are rarely useful across Education and B2C models. A premium programme with high-touch delivery should not be judged like a low-cost subscription product. A company with annual upfront payments has a different cash profile from one with instalment collections. The useful comparison is against your own margin structure, cohort history, and capacity to finance growth.
What patterns suggest that acquisition economics are improving?
- Customers acquired through a channel maintain or improve contribution after acquisition costs.
- Payback remains stable or improves as volume increases.
- Conversion from qualified demand to customers is consistent without excessive discounting.
- Refunds, support burden, and delivery costs remain controlled.
- Newer cohorts show customer outcomes comparable to or better than prior cohorts.
What patterns suggest that growth is hiding an economic problem?
- CAC rises while contribution-margin LTV remains flat or declines.
- More leads enter the funnel, but fewer prospects who fit the intended customer profile become customers.
- Sales conversion declines despite stable traffic volume and apparent lead volume.
- Refunds, returns, chargebacks, or service demands rise after purchase.
- Payback extends beyond the business’s cash tolerance.
Which growth bottlenecks can CAC, LTV, and payback reveal?
CAC, LTV, and payback can reveal where the revenue machine is losing economic value. They do not diagnose the cause automatically, but they direct leadership to the right part of the system.
A rising CAC may indicate more expensive attention, weaker creative, reduced channel efficiency, or a smaller reachable audience. It may also be the result of lower conversion after the click, not a media problem. A falling LTV may indicate offer mismatch, poor onboarding, retention weakness, high fulfilment cost, or a product experience that does not create repeat demand.
How can you tell whether the problem is traffic quality or sales conversion?
Compare stage-to-stage behavior. If visitors or leads increasingly match the intended customer profile, engage with the right messages, and reach sales conversations, but close rates fall, the likely constraint is in offer positioning, sales execution, pricing, proof, or buyer readiness.
If acquisition brings a growing share of people who do not fit the target customer profile, lack the relevant need, or disengage before meaningful evaluation, the issue is more likely audience selection, message-market fit, channel context, or the promise used to generate the response.
Then check downstream outcomes. If customers from one source convert but refund more often or require disproportionate support, that source may be optimising for a response that does not predict customer fit.
How can you tell whether the problem is the offer or the delivery model?
Look at the sequence after purchase. High early refunds can indicate that the offer created expectations the experience does not meet. Low completion or engagement can indicate weak onboarding, poor product fit, or insufficient customer support. Strong demand combined with thin contribution may indicate that the delivery model itself needs redesign.
Do not assume the answer is more marketing. If delivery economics are the constraint, adding customers can worsen the problem.
What should a CEO see on a unit economics dashboard?
A CEO should see a compact commercial view that connects acquisition investment to conversion, contribution, customer outcomes, payback, and cash. The purpose is not reporting volume. It is faster recognition of the constraint that deserves attention.
The dashboard should make it possible to see whether the business is acquiring the right customers, converting them efficiently, serving them profitably, and recovering cash quickly enough to continue investing.
Which metrics need to be viewed together?
CAC should be viewed alongside customer volume, conversion through the key commercial stages, contribution margin, refund behavior, retention or repeat purchase, and payback timing. Any one metric can mislead when separated from the others.
For example, a lower CAC is not necessarily progress if it is accompanied by weaker retention. Higher CAC is not automatically failure if the acquired cohort has stronger contribution, faster collection, and better repeat behavior. This is the core of how CAC should be interpreted: as part of a commercial system, not a platform scorecard.
How often should the numbers be reviewed?
Operational signals may need regular review where spend, lead flow, or sales conversion changes quickly. Cohort economics need a longer lens because retention, refunds, repeat purchase, and delivery costs take time to mature.
Review cadence should match the business model. A short-cycle ecommerce business can learn faster from recent cohorts than a high-consideration education purchase with a longer sales and delivery cycle. The mistake is judging long-term customer value before the relevant customer behavior has had time to occur.
How should CAC LTV insight change spend, hiring, and agency decisions?
CAC LTV insight should change decisions by directing investment toward the actual constraint. A company should not increase spend, add headcount, or replace an agency simply because a headline metric moved in the wrong direction.
External partners can execute well within a system that has a weak offer, poor sales conversion, unreliable measurement, or unprofitable delivery. Equally, a strong underlying system can still suffer from weak channel execution. Leadership must separate the vendor question from the system question.
The principles in Marketing Agency Performance: How CEOs Should Evaluate Agency Performance apply here: assess an agency against the part of the commercial system it can reasonably influence, while maintaining executive visibility of the broader economics.
When is it rational to increase acquisition investment?
Increasing acquisition investment is rational when there is credible evidence that margin-adjusted customer value, payback timing, conversion capacity, delivery capacity, and available cash can support it. Lower platform costs alone are not enough.
Leadership should also confirm that scaling will not reduce customer experience, stretch sales capacity, increase fulfilment delays, or create service costs that invalidate the economics.
When should you fix the funnel or retention system before hiring more execution?
Fix the funnel or retention system first when the evidence shows that additional execution would intensify an existing break. Examples include a sales team unable to convert qualified demand, a checkout process that loses ready buyers, high refund rates after purchase, or retention that fails to support the assumed LTV.
Hiring more marketers, salespeople, or agencies in these conditions may increase activity while leaving the economic constraint untouched.
How should you evaluate an agency when CAC is rising?
Start by identifying where the deterioration occurred. Did media costs rise? Did click-to-lead conversion fall? Did lead-to-customer conversion weaken? Did the customer mix change? Did refunds, delivery costs, or retention worsen? Did attribution or cost definitions change?
If the issue is media efficiency, creative testing, audience selection, landing-page performance, or channel management, agency execution may be central. If the issue is offer fit, sales conversion, product experience, pricing, fulfilment, or retention, changing the agency may not solve the problem.
What should you check in a growth audit before making a scaling decision?
Before making a material scaling decision, verify whether the evidence supports profitable and financeable growth. A growth audit should establish whether the company has a measurement issue, an acquisition issue, a conversion issue, a retention issue, a delivery-economics issue, or a cash-recovery issue.
This is the practical value of reviewing CAC and LTV alongside the wider analysis in LTV Unit Economics: A CEO-Level Growth Guide, Unit Economics CAC: A CEO-Level Growth Guide, and Unit Economics Case Study: A CEO-Level Growth Guide.
What evidence should be verified before you call a channel scalable?
- CAC definitions are consistent and include costs relevant to the decision.
- Customer cohorts are mature enough to support the LTV and retention assumptions being used.
- Contribution margin accounts for refunds, fulfilment, service, commissions, and other material variable costs.
- Conversion remains stable across the stages that matter, from demand through customer acquisition.
- Payback fits the company’s cash position and growth plans.
- Operations can serve a larger customer base without eroding delivery quality or margin.
- Recent customer outcomes support the claim that the channel produces commercially valuable customers, not only initial transactions.
If you are about to make a significant spend, hiring, or agency decision and cannot answer these questions with confidence, a Growth Audit is a relevant next step. The objective is not more reporting. It is clarity on the one constraint that must be improved before growth capital is committed.
\nWhen should a CEO watch the VSL and book a Growth Audit?
\nWatch the VSL and then book a Growth Audit when CAC, LTV, margin, or payback is being debated without a shared model or clear next decision. The audit can identify the constraint and clarify whether the business should change spend, offer, conversion, retention, hiring, or agency scope.
\n\nFrequently asked questions about unit economics, CAC, and LTV
\n\n\nThere is no universal ratio that is healthy for every business. The right interpretation depends on contribution margin, payback timing, customer retention, sales cycle, cash availability, and delivery costs. A ratio based on revenue rather than contribution can materially overstate the quality of acquisition economics.
Calculate CAC payback by dividing the acquisition cost by the contribution margin generated per customer over a consistent period. Then assess whether the resulting time to recover CAC works within your cash model, collection schedule, and operating capacity.
Yes. LTV used for executive growth decisions should reflect the economic contribution of the customer, not just revenue. Gross margin, direct delivery costs, fulfilment, refunds, payment processing, support, and other variable costs can materially change the result.
Yes, if later contribution from retention, repeat purchases, renewals, or upgrades reliably recovers CAC within a cash timeline the business can fund. The key issue is evidence. Leadership needs mature cohort data, margin visibility, and a realistic view of payback before treating future customer value as a basis for aggressive growth.
One Response