Marketing performance is working when it creates qualified demand that converts into collected revenue and acceptable margin at a pace the business can fund. It is not working simply because traffic, leads, clicks, or platform-reported conversions are rising.
For a CEO, the question is not whether marketing activity looks busy. The question is whether the company’s acquisition engine is producing profitable growth without creating a cash, fulfillment, or sales-capacity problem downstream.
That requires a business-level view of demand, conversion, CAC, payback, cash collection, and margin. Anything less can make a weak growth system look healthy for longer than it should.
What does marketing performance mean at the CEO level?
At the CEO level, marketing performance means marketing’s measurable contribution to the company’s ability to acquire the right customers profitably. It connects demand generation to sales outcomes, revenue, cash, and margin.
Digital marketing performance matters, but it is only one part of the picture. A campaign can appear efficient inside an ad platform while the business experiences poor sales conversion, delayed collections, high refunds, weak retention, or shrinking contribution margin.
Why are clicks, impressions, and lead volume not enough to judge performance?
Clicks and impressions show whether people encountered a message. Lead volume shows whether some people responded. None of these measures proves that the business acquired customers it can profitably serve.
A lead count can increase because targeting became broader, a form became easier to complete, or an offer attracted people who want information but are unlikely to buy. That is not necessarily a media problem. It may be a targeting, offer, qualification, or follow-up problem.
CEOs should treat activity metrics as diagnostic signals, not as proof of commercial performance.
What business outcomes should marketing influence?
Marketing should be accountable for influencing the quality and quantity of demand entering the revenue engine. Depending on the model, that includes inquiries from the right audience, sales-accepted opportunities, purchases, booked calls that attend, qualified applications, and repeatable customer acquisition economics.
Marketing cannot own every outcome alone. Sales execution, offer design, pricing, operations, fulfillment, and customer experience also affect results. But marketing should be measured in the context of the full system rather than isolated from it.
How should marketing performance connect to the company’s revenue goal?
A revenue target is useful only when leadership can explain the demand, conversion, capacity, and cash assumptions required to reach it. Marketing performance should show whether those assumptions remain credible.
Start with the commercial outcome the business needs, then work backward through the major stages that must support it. The objective is not to create a complicated forecast. It is to expose where the plan depends on an assumption that may not hold.
What must be true between new demand and collected revenue?
For new demand to become collected revenue, several things must happen: the right people must enter the funnel, they must receive a compelling offer, the sales or checkout process must convert them, and the company must collect payment while delivering the product or service at a viable margin.
In education businesses, that can include inquiry-to-application conversion, enrollment, payment-plan collection, attendance, completion, and refund behavior. In B2C businesses, it may include purchase conversion, average order value, repeat purchase, fulfillment costs, and return rates.
Each stage changes the commercial meaning of the one before it. Strong top-of-funnel demand cannot compensate indefinitely for a weak close rate or poor collection rate.
Why should revenue targets be tested against conversion capacity and cohort timing?
Revenue targets often fail because the company assumes demand created this month will become cash this month. That may not be true.
Longer sales cycles, payment plans, cohort start dates, onboarding capacity, delayed collections, and refund windows all affect when marketing activity becomes recognized revenue and usable cash. A business can hit a bookings number while still experiencing a cash gap.
The CEO’s role is to ensure the growth plan respects timing, capacity, and economics rather than treating a revenue target as an instruction for marketing to generate more leads.
Which leading indicators should CEOs watch before revenue misses?
CEOs should monitor a small number of leading indicators that reveal whether the revenue engine is weakening before the financial result is final. The most useful indicators sit close to the current constraint.
Revenue is a lagging outcome. By the time a monthly revenue miss is clear, the underlying issue may have been building across demand, qualification, conversion, or follow-up for weeks.
How can qualified demand reveal a problem earlier than booked revenue?
Qualified demand is more informative than raw inquiry volume because it shows whether the market response is commercially relevant. If inquiry volume is stable but the number of prospects matching the offer, buying criteria, and sales process falls, a revenue issue may be developing even before bookings decline.
For example, a company may see a healthy cost per lead while the proportion of inquiries that meet the program’s eligibility, budget, urgency, geography, or intended use criteria falls. The acquisition system is producing contacts, but fewer contacts are becoming realistic customers.
Which conversion changes can signal a funnel or sales issue?
Changes in landing-page conversion, application completion, booked-call attendance, sales acceptance, close rate, checkout completion, and payment collection can all point to an emerging constraint.
The key is not to react to every daily movement. Look for material changes that persist long enough to warrant investigation, then determine whether the issue is isolated to a channel, offer, audience, sales team, or operational step.
What makes demand qualified enough to count in marketing performance?
Demand should count as qualified when there is evidence that the prospect fits the offer, has a plausible ability to buy, shows meaningful intent, and can move through the company’s actual sales or purchase process.
That definition should be specific to the business. A qualified inquiry for a low-consideration consumer product is not the same as a qualified applicant for a high-ticket education program.
How should leadership distinguish inquiry volume from sales-ready demand?
An inquiry is a person who has raised a hand. Sales-ready demand is a person whose situation, intent, and next action make a commercial conversation or purchase plausible.
Leadership should be able to see where inquiries stop progressing. Are prospects failing to meet the offer’s requirements? Are they unwilling to pay? Are they not responding to follow-up? Are they booking but not attending? Are they reaching sales but not receiving a timely or persuasive response?
These are different failures. Treating them all as “low-quality leads” prevents the company from finding the actual constraint.
When does a qualification problem originate in targeting, offer, or follow-up?
A qualification issue can originate upstream when targeting reaches the wrong audience or creative makes a promise the offer cannot fulfill. It can originate in the offer when the value proposition attracts curiosity without sufficient purchase intent. It can also originate after lead capture when slow response times, weak nurture, poor contactability, or inconsistent sales follow-up prevent viable prospects from progressing.
The correct intervention depends on where the evidence breaks. Better targeting will not fix an uncompetitive offer. New creative will not fix a sales process that fails to contact qualified prospects promptly.
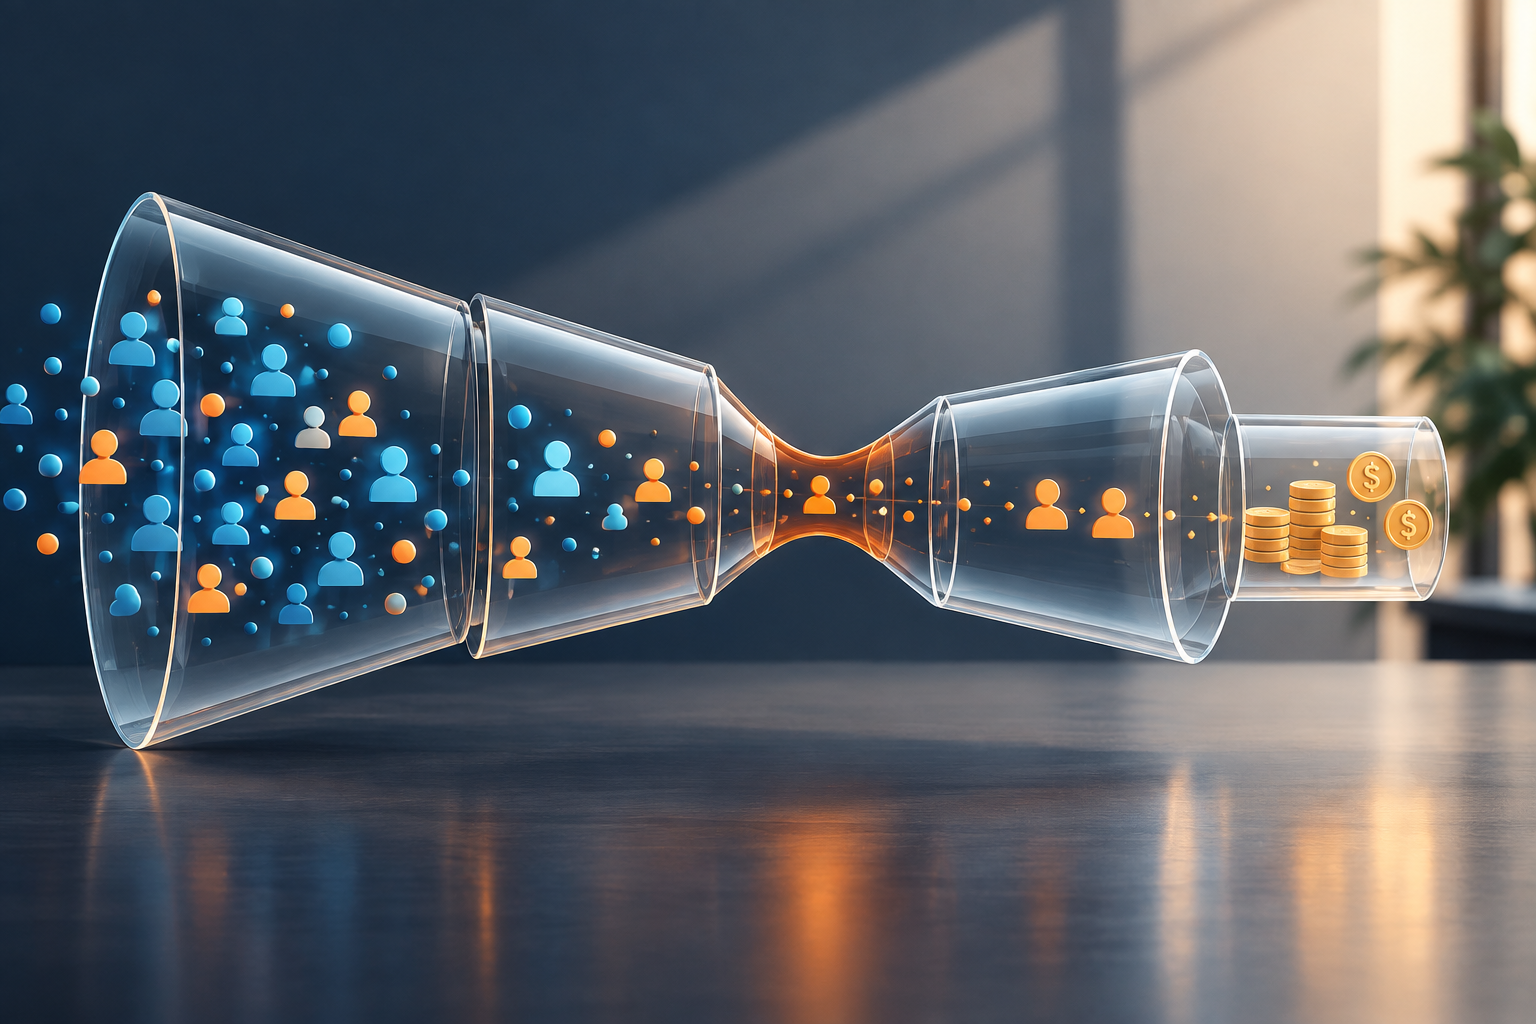
How do conversion, cash, and margin belong in the same scorecard?
Conversion, cash, and margin belong together because each answers a different part of the same commercial question: can the business acquire customers in a way that produces usable profit?
Conversion shows whether demand becomes customers. Cash shows when the business actually receives funds. Margin shows what remains after the direct costs of serving those customers. Revenue alone cannot answer all three questions.
Why can revenue growth still create a cash problem?
Revenue growth can create a cash problem when the company pays acquisition costs before it collects from customers, particularly when payment plans extend collection over time. It can also happen when increased sales require upfront delivery, inventory, support, instructor, fulfillment, or onboarding costs.
A business may be growing on paper while its available cash becomes tighter. That does not mean marketing should stop automatically. It means leadership needs to assess acquisition timing against collection timing, available cash, and the reliability of the customer cohort.
How should contribution margin change the interpretation of acquisition performance?
Contribution margin changes the meaning of every acquisition result. A customer acquired at an acceptable CAC may still be commercially unattractive if discounts, payment processing, delivery, fulfillment, refunds, support, or variable service costs leave too little margin.
Conversely, an acquisition cost that appears high in isolation may be rational when gross margin is strong, customer retention is demonstrated, cash payback is manageable, and the company has capacity to serve the additional demand.
How should CAC, payback, and unit economics shape marketing decisions?
CAC should shape marketing decisions only alongside payback timing, gross margin, conversion performance, and cash availability. A lower CAC is not automatically better if it comes from customers who convert poorly, refund frequently, or produce weak margin.
Customer acquisition cost is the cost required to acquire a customer through a defined acquisition effort. Payback asks how long it takes for the gross profit or contribution generated by that customer to recover the acquisition cost. Both need to be interpreted in the context of the company’s model.
Why is CAC incomplete without payback timing and gross margin?
CAC has no universal “good” number. A company with upfront collection and healthy margin can tolerate a different acquisition profile from a company that collects over many months and has substantial delivery costs.
For a fuller executive view, see Unit Economics: A CEO-Level Growth Guide. The practical point is simple: acquisition is fundable only when the company can carry the cash timing and preserve enough margin to make the growth worthwhile.
When can a higher acquisition cost still be commercially rational?
A higher acquisition cost can be rational when it brings customers with stronger conversion, better payment behavior, lower refund risk, higher contribution margin, or meaningful repeat-purchase potential. It can also be justified when a business is deliberately entering a segment that has strategic value and the economics remain supportable.
That judgment requires evidence. It should not rest on a platform dashboard or a broad assumption that customer lifetime value will eventually solve the problem.
What can platform and agency reports tell you, and what can they not tell you?
Platform and agency reports can identify delivery patterns, audience response, conversion signals, and testable hypotheses. They cannot replace reconciliation with the company’s sales records, payment data, revenue reporting, and margin reality.
This is why CEOs should understand both Marketing Agency Performance: How CEOs Should Evaluate Agency Performance and Agency Performance Metrics: How CEOs Should Evaluate Agency Performance. An agency report may accurately describe platform results while still failing to answer whether the overall revenue system is performing.
Why can attribution assign credit differently from financial records?
Attribution is a method for assigning conversion credit across interactions. Different models can credit the same customer journey differently depending on the rules used. Marketing leaders should understand how attribution models assign credit across touchpoints, but they should not mistake attribution for a complete financial ledger.
A platform may claim credit for a conversion because it recorded an interaction before the purchase. The company’s financial records may show a different customer count, different revenue timing, or a different view of which channels influenced demand. Both views can be useful, but they answer different questions.
Analytics data may also be incomplete or subject to modeled reporting. Leaders should understand why recent attributed conversion data can change before treating early reports as final.
What should CEOs ask when platform performance and revenue performance disagree?
Ask whether the disagreement is caused by timing, tracking, attribution rules, sales conversion, payment collection, or a genuine deterioration in customer quality. Then reconcile the major stages: spend, inquiries, qualified demand, sales activity, purchases or enrollments, collections, and margin.
If platform efficiency improves while revenue weakens, do not assume the platform is wrong or the agency is failing. Investigate whether the business is acquiring a different type of prospect, whether sales conversion changed, or whether a collection and fulfillment issue is masking the true result.
How should marketing performance tracking work across daily and weekly reviews?
Marketing performance tracking should use daily review to catch material disruption and weekly review to make commercial decisions. Daily data is useful for operational awareness. Weekly trends are more useful for judging direction and allocating management attention.
What should be reviewed daily without overreacting to normal volatility?
Daily review should focus on significant delivery changes, tracking interruptions, broken conversion paths, sharp shifts in spend pacing, and clear drops in high-intent actions. It is a control function, not a reason to redesign the growth plan every morning.
Daily volatility is normal, especially in lower-volume funnels and higher-consideration offers. A single weak day does not establish a trend.
What decisions belong in a weekly marketing performance review?
A weekly review should assess whether demand quality, conversion, acquisition economics, sales follow-up, collections, and margin are moving in the right direction. It should also establish the current constraint and decide what needs investigation or adjustment.
The best meetings end with a clear management decision, not a longer list of reports to produce. That decision may be to protect an effective program, investigate a conversion decline, tighten qualification, improve sales execution, revisit the offer, or reassess the economics before expanding investment.
How do CEOs identify the single constraint limiting growth?
CEOs identify the growth constraint by locating the point where economic throughput is currently restricted. The constraint may be demand generation, qualification, conversion, sales capacity, collection, retention, fulfillment capacity, or margin.
The Profit CMO perspective is Constraint First: improve the limiting point in the revenue machine before trying to optimize everything at once.
Why does optimizing every metric at once dilute management attention?
When every metric becomes a priority, the team produces more activity without resolving the issue that is actually limiting growth. Improving traffic while sales capacity is constrained can create backlog. Improving sales scripts while the offer attracts the wrong audience can create frustration. Reducing CAC while contribution margin deteriorates can create an illusion of progress.
A clear constraint gives the company a better standard for evaluating work. The question becomes, “Did this action improve the limiting point?” rather than, “Did we do more marketing?”
How can leaders tell whether the constraint is in traffic, conversion, sales, or economics?
Look at the handoffs. If enough of the right people are not entering the funnel, the constraint is likely demand or targeting. If they enter but do not take the intended next step, investigate the offer, message, user experience, or qualification process. If qualified prospects reach sales but do not progress, inspect responsiveness, capacity, process, and close performance.
If customers are acquired but the business cannot collect cash, serve them profitably, or retain them, the constraint is economic or operational rather than top-of-funnel marketing.
What are the most effective ways to improve marketing performance?
The most effective ways to improve marketing performance begin with evidence, not a generic list of tactics. Protect measurement integrity, identify the constraint, validate downstream economics, and make the change most likely to improve the restricted part of the system.
Marketing performance optimization is not synonymous with reducing cost per click or producing more leads. It is the disciplined improvement of profitable throughput through the revenue engine.
When should the business improve the offer instead of the media plan?
Improve the offer when the market is seeing the message but the value exchange is not compelling enough to produce qualified action or conversion. Symptoms can include weak landing-page conversion across channels, high interest but low purchase intent, repeated price objections, or prospects who do not understand the outcome they are buying.
A media plan can amplify a clear and credible offer. It cannot reliably repair an offer that is confusing, undifferentiated, poorly timed, or misaligned with the buyer’s actual problem.
When should leadership fix follow-up or sales execution before changing acquisition?
Fix follow-up or sales execution first when qualified prospects are entering the system but response time, contact rates, appointment attendance, sales acceptance, or close rates are weak. Increasing acquisition under those conditions usually increases waste rather than growth.
The CEO should ensure the company can handle the demand it already pays to create before asking marketing to produce materially more of it.
When should weak performance trigger a budget, funnel, sales, or agency change?
Weak performance should trigger the intervention that matches the evidence. A budget change is appropriate only when the economics, conversion path, cohort timing, and cash position support it. A funnel or sales change is appropriate when viable demand is being lost after acquisition. An agency change is appropriate when the vendor is clearly unable or unwilling to execute against an agreed commercial standard.
Not every underperforming campaign is an agency problem. Agencies can execute well within a system that has a weak offer, broken tracking, slow sales follow-up, poor pricing, or unworkable unit economics. Equally, a capable business can be held back by a vendor that reports activity without taking responsibility for the quality of execution and learning.
When is a budget change justified by the economics?
A budget change is justified when the business understands its acquisition cost, payback timing, gross margin, conversion performance, cohort behavior, and available cash. It should also understand whether additional volume will encounter capacity constraints in sales, delivery, support, or fulfillment.
Do not increase spend because a channel’s reported CPA looks attractive in isolation. Do not cut spend simply because CAC rose over a short period. First determine whether the change reflects normal variation, an attribution issue, a conversion problem, a margin issue, or a true decline in acquisition efficiency.
When is an agency change appropriate rather than a distraction?
An agency change is appropriate when the execution problem is clearly within the vendor’s control: weak strategic discipline, poor campaign management, unreliable reporting, inadequate testing, lack of transparency, missed commitments, or an inability to respond to evidence.
It is a distraction when leadership uses the agency as a substitute for fixing internal constraints. Before making a change, clarify what the agency owns, what the company owns, and what the evidence says about the limiting point. Marketing Agency Accountability Frameworks: What CEOs Should Expect can help structure that conversation.
\nHow should a CEO turn marketing performance into an operating decision?
\nWhat should the scorecard cause leaders to do?
\nA scorecard should make the next decision clearer. It should show whether the constraint is moving, which leading signals deserve attention, what customer quality looks like, and whether the economics support more investment. If the report cannot change a priority, a budget, a funnel decision, or an agency conversation, it is not doing enough work.
\nWhen should a CEO watch the VSL and book a Growth Audit?
\nWatch the VSL and then book a Growth Audit when performance discussions are producing more metrics but not more agreement. The audit can identify whether the next move belongs in acquisition, conversion, sales, retention, measurement, or leadership capacity.
\n\nFrequently asked questions about marketing performance
\n\n\nMarketing performance is the broader operating picture: demand quality, conversion, CAC, payback, cash, margin, and the current constraint. Marketing ROI is a narrower financial calculation comparing return to investment. ROI can be useful, but it may hide timing, collection, and margin issues that matter to the CEO.
Review the measures closest to the current constraint, along with qualified demand, conversion through the key handoffs, CAC, collection performance, contribution margin, and material changes in capacity. The exact mix should reflect the business model rather than a generic dashboard template.
Use attribution as one source of evidence, then reconcile it with CRM, sales, payment, and financial records. Look for directional patterns across the full customer journey rather than expecting one platform or attribution model to prove the complete causal story.
Trace the gap between inquiry and collected revenue. Determine whether the new inquiries match the offer, whether they are accepted by sales, whether follow-up is effective, whether conversion changed, and whether collections or refunds are affecting the outcome. Do not treat higher lead volume as progress until the downstream economics support it.
2 Responses